
The last few months of the year are when a little planning can save the most in taxes. Many of the best moves have a December 31 deadline, and once January comes they are gone for another year. Here is the checklist I go through with clients each fall. All figures are for the 2026 tax year.
1. Put investment losses to work
If you have realized capital gains this year, look for investments in your taxable accounts that are worth less than you paid. Selling them can offset those gains. Long-term gains (on assets held more than a year) are taxed at a top federal rate of 20%, plus the 3.8% net investment income tax for higher earners. Short-term gains are taxed as ordinary income, at rates up to 37%.
If your losses exceed your gains, you can deduct up to $3,000 against ordinary income and carry the rest forward to future years. Just remember that taxes are only one reason to sell. An investment you still believe in should not be sold only to book a loss. Five Strategies for Tax Efficient Investing goes into more detail.
2. Max out retirement plan contributions
- 401(k), 403(b), 457, and TSP: up to $24,500. Those 50 and older can add $8,000 (total $32,500). Those age 60 to 63 can add $11,250 instead (total $35,750). Contributions must come out of a paycheck by December 31, so check with HR now if you want to increase your last few deferrals.
- SIMPLE IRA: up to $17,000, plus $4,000 at 50 or older, or $5,250 at age 60 to 63.
- IRA: up to $7,500, or $8,600 at 50 or older. You have until the tax filing deadline in April 2027 to make a 2026 contribution.
If your income is low this year, making Roth contributions instead of pre-tax contributions may give you more long-term benefit. Many employer plans now offer a Roth option.
3. Take your required minimum distributions
RMDs from traditional IRAs and most workplace plans begin at age 73, or 75 if you were born in 1960 or later. After your first year, the deadline is December 31. For your very first RMD, you can wait until April 1 of the following year, but then you will take two distributions in one tax year.
Missing an RMD triggers a 25% penalty on the amount you should have withdrawn, reduced to 10% if you correct it promptly. That is much lower than the old 50% penalty, but still worth avoiding. If you inherited an IRA, check whether annual distributions are required on that account too.
4. Give to charity from your IRA
If you are 70½ or older, a qualified charitable distribution (QCD) lets you send up to $111,000 in 2026 directly from your IRA to a charity. The money is not included in your taxable income, and it counts toward your RMD if you have one. You don’t need to itemize to benefit. The money must go straight from the IRA to the charity, and the deadline is December 31.
5. Plan your charitable gifts around the new rules
Several charitable deduction rules changed starting in 2026:
- If you take the standard deduction, you can now deduct up to $1,000 ($2,000 for married couples filing jointly) of cash gifts to public charities. Gifts to donor-advised funds do not qualify.
- If you itemize, only the portion of your charitable gifts above 0.5% of your adjusted gross income is deductible. For example, with $400,000 of AGI and $10,000 of gifts, $8,000 is deductible.
- If you are in the 37% bracket, the tax benefit of itemized deductions is capped at 35%.
- The limit on deductions for cash gifts to public charities remains at 60% of AGI.
The standard deduction for 2026 is $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household. Taxpayers 65 and older may also be able to claim an additional deduction of up to $6,000 through 2028, subject to income limits. The cap on state and local tax deductions is $40,400 for 2026.
With a large standard deduction, many people itemize only every other year. “Bunching” two years of gifts into one year, often through a donor-advised fund, can get you over the itemizing threshold in that year while you take the standard deduction in the next.
6. Consider a Roth conversion
If your income is lower than usual this year, converting part of a traditional IRA to a Roth IRA may let you pay tax at a lower rate now in exchange for tax-free growth later. Conversions must be done by December 31. See Converting a Traditional IRA to a Roth IRA for how to decide how much to convert.
7. Use your health accounts
If you have a high-deductible health plan, you can contribute up to $4,400 to a health savings account for self-only coverage or $8,750 for family coverage in 2026, plus $1,000 if you are 55 or older. You have until the tax filing deadline to fund an HSA. If you have a flexible spending account through work, check your balance; many FSAs require you to spend most of it by year-end. More in Lowering Your Tax Bill with an HSA.
8. Check your withholding
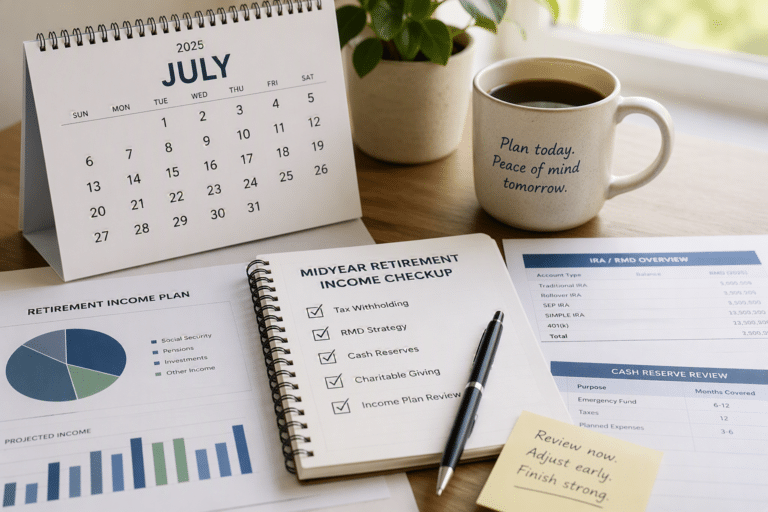
If you have income without withholding, such as IRA withdrawals, pension income, or investment income, make sure enough tax has been paid to avoid an underpayment penalty. A final estimated payment or an increase in withholding before year-end can help. My midyear retirement income checkup walks through this.
9. Don’t forget 529 plans
Some states, including New York, offer a state income tax deduction for contributions to the home-state 529 plan. Contributions usually must be made by December 31 to count for the year.
10. Look beyond taxes
Year-end is also a good time to review the rest of your plan:
- Is your emergency fund still the right size? Three to six months of expenses is a common rule of thumb, but retirees and people with less stable income often need more.
- Do your beneficiary designations on retirement accounts and insurance policies still match your wishes?
- Has anything happened this year that means your will, health care proxy, or power of attorney should be updated? See Five Estate Planning Mistakes Successful Families Make.
These are general ideas, not tax advice. Talk with your tax professional and financial advisor about which of these steps fit your situation before the year runs out.
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.